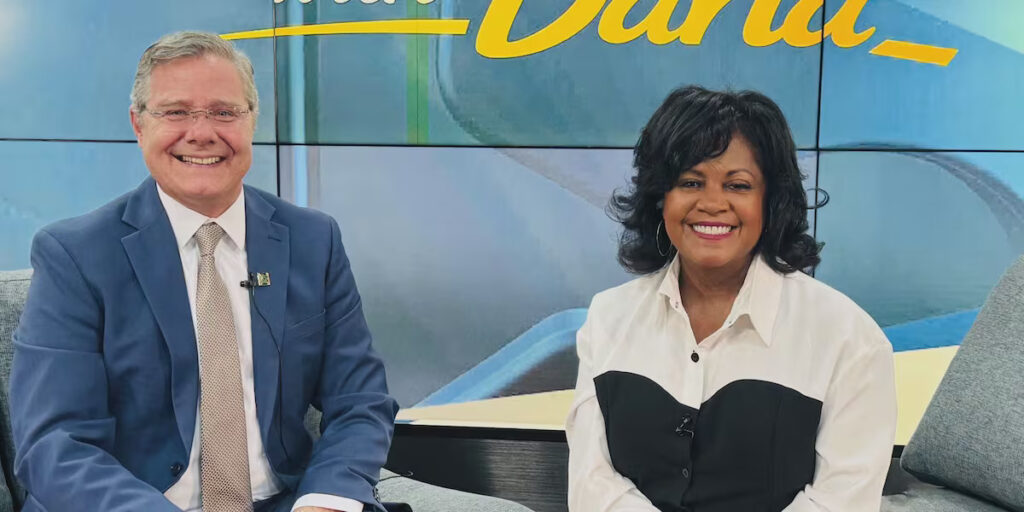
Attorney Tracy P. Curtis of The Glenn Armentor Law Corporation joined KADN’s MidDay with Darla to warn Louisiana drivers that “full coverage” auto insurance may not offer the protection many people think it does. During the segment, he explained the differences between the main types of auto insurance coverage and cleared up some common misconceptions that can leave accident victims underprotected when they need help most.
What Does “Full Coverage” Actually Mean?
Many drivers are surprised to learn that “full coverage” is not an official type of insurance policy. You won’t find it defined in Louisiana law, and it doesn’t appear as a coverage line on your policy. It is a sales term, and it usually refers to a combination of three coverages:
Liability coverage pays for injuries and property damage you cause to other people. This is the coverage Louisiana law requires.
Collision coverage pays to repair or replace your own vehicle after a crash, regardless of who was at fault.
Comprehensive coverage pays for damage to your vehicle from non-collision events, such as theft, hail, flooding, fire, or hitting a deer.
These coverages protect your car and protect other people from you. What they often do not do is protect you if you are injured by a driver who has little or no insurance. That is where the “full coverage” myth can be costly.
Louisiana’s Minimum Insurance Requirements Are Low
Louisiana requires drivers to carry liability insurance of at least 15/30/25. That means:
- $15,000 for bodily injury to one person
- $30,000 for bodily injury to all people in one accident
- $25,000 for property damage per accident
A single trip to the emergency room, followed by imaging, specialist visits, and physical therapy, can quickly exceed $15,000. Add lost wages and pain and suffering, and a serious injury claim can be worth many times the at-fault driver’s policy limit. If the driver who hit you carries only the minimum, or has no insurance at all, your recovery may be capped far below what your injuries are actually worth.
The Coverage That Protects You: Uninsured/Underinsured Motorist (UM)
Uninsured/underinsured motorist coverage, usually called UM coverage, steps in when the at-fault driver has no insurance, leaves the scene in a hit-and-run, or doesn’t carry enough insurance to cover your damages. In those situations, your own UM coverage can make up the difference, up to your policy limits.
Under Louisiana law, insurers must provide UM coverage equal to your bodily injury liability limits unless you reject it or choose lower limits in writing on a form approved by the Louisiana Commissioner of Insurance. That means many drivers who believe they have “full coverage” may have signed away some or all of their UM protection when they bought their policy, often to lower their premium, and without fully understanding what they were giving up.
Louisiana’s UM form also offers an “economic-only” option. This cheaper choice covers losses like medical bills and lost wages but does not cover general damages such as pain and suffering. For many injured people, that is a significant gap.
Other Coverages Worth Reviewing
Beyond UM, several optional coverages can make a big difference after a crash:
- Medical payments (MedPay): Helps pay medical bills for you and your passengers regardless of fault, often quickly, while fault is still being sorted out.
- Rental reimbursement: Covers a rental car while your vehicle is being repaired.
- Towing and roadside assistance: Helps with immediate costs at the scene.
- Gap coverage: If you have a loan or lease, pays the difference between what you owe and what your totaled car is worth.
How to Check Whether You’re Really Covered
The best way to find out what you actually have is to review your declarations page, the summary page of your policy that lists each coverage and its limits. Look for:
- Your bodily injury liability limits. Are they higher than the state minimum?
- Whether UM coverage is listed, and whether it matches your liability limits.
- Whether your UM coverage is full or economic-only.
- Whether you have MedPay, rental reimbursement, and any other coverage you’re counting on.
If anything is unclear, ask your agent to explain it in plain language, and ask for a copy of any UM selection or rejection form you signed. Reviewing your coverage now, before an accident, is the best way to avoid an unpleasant surprise later.
Injured in a Crash? Your Coverage May Be More Complicated Than It Seems
After an accident, figuring out which policies apply, whether a UM rejection form is valid, and how much coverage is really available can be complicated. Insurance companies do not always volunteer every source of coverage you may be entitled to. An experienced Louisiana auto accident lawyer can review your policy and the at-fault driver’s policy to identify every avenue of recovery.
If you’ve been hurt, these resources from our team can help you take the next steps:
- What to Do at the Scene of a Car Accident in Louisiana
- Why Medical Treatment Is Important After an Accident
- What to Expect When Filing an Injury Claim in Louisiana
- Property Damage Claims in Louisiana: What Insurance Companies Don’t Want You to Know
Frequently Asked Questions
Is “full coverage” required in Louisiana?
No. Louisiana only requires liability coverage of at least 15/30/25. However, if you have a car loan or lease, your lender will likely require collision and comprehensive coverage.
Does full coverage include uninsured motorist coverage?
Not necessarily. “Full coverage” usually refers to liability, collision, and comprehensive. Whether you have UM coverage, and how much, depends on your policy and on any selection or rejection form you signed.
What happens if I’m hit by a driver with no insurance?
If you have UM coverage, you can make a claim under your own policy for your injuries, up to your UM limits. Without UM coverage, your options for recovering compensation may be very limited.
Can I still have UM coverage if I don’t remember rejecting it?
Possibly. Louisiana requires UM rejections to be made in writing on a specific form. If the form was not properly completed, UM coverage may apply by law. An attorney can review the paperwork to find out.
Talk to a Lafayette Car Accident Lawyer Today
For nearly 50 years, The Glenn Armentor Law Corporation has helped accident victims across Acadiana and South Louisiana recover the compensation they deserve, with over $530 million in case results. If you’ve been injured in a crash and aren’t sure what your insurance covers, our experienced attorneys can help.
Call us today at (337) 233-1471 or request a free case evaluation. If we don’t win, you don’t pay.
This article is for general informational purposes only and is not legal advice. For advice about your specific situation, contact our office.